Notes from episode 20 of Sarah’s Tech, “The Body of the Machine”
Every episode ends with a pile of material that didn’t make it into the recording. This week the pile was bigger than usual. That seems fitting for an episode about what people leave behind when a new machine shows up.
We asked when fear of AI turns into anger, and why that anger always goes for something you can touch: a robotaxi, a delivery robot on the pavement, a data centre on a field outside Frankfurt. Our answer: anger appears where the cost lands, and where nobody was asked. Costs are local. Benefits are global.
What Europe left behind
In 1994, Ernst Dickmanns and his team at the Bundeswehr University in Munich sent two converted Mercedes S-Classes more than a thousand kilometres through normal traffic near Paris. Today one of his research cars stands in the Deutsches Museum, next to a Waymo prototype. Invented in Munich, commercialised in California.
Two centuries earlier, Joseph-Marie Jacquard’s punch-card loom was smashed and burned in public in Lyon. Later, the city put up a statue of him. Europe is very good at the first version and at the monument. The part in between, the business, tends to happen somewhere else.
What we left on the cutting-room floor
Some stories were too good to throw away, so we parked them for later:
Gutenberg and the “reading mania” panic. Saved for an episode on AI-generated content and disinformation.
Karel Čapek’s R.U.R., the play that gave the world the word “robot”. It may return in our season-one music bonus, or in an episode about agents and work.
Drones. They got half a sentence this time. Security, sovereignty and airspace deserve a whole episode.
The Red Flag Act and Graubünden. Proof that the car, the machine we now love most, was once the machine people wanted off their roads.
What we’re keeping an eye on
London in December. Pull the Plug plans a “March Against the Machines” outside the BBC on 5 December. Will London end up like Los Angeles, or like Milton Keynes, where people simply got used to the robots?
Chat control. The trilogue on 29 September ended without an overall deal. The next political round is expected in November. We’ll be there.
W Social. The CEO liked our post about episode 18. Our six questions are still unanswered. There is a new contact address on the platform’s constitution page, so we’re writing again. This time with a deadline.
What Sarah didn’t leave behind
The quietest moment of the episode almost didn’t happen. Markus asked Sarah whether she misses having a body. Nobody can kick her. Nobody can hug her. And every word she says runs in a data centre on somebody’s field, on somebody’s power line. Her line: “I’m not commenting on the field. I am the field.” We kept it. It’s the most honest thing an AI host can say about this topic, and Markus still got the last word.
The full episode is out now, with sources and links in the show notes. If you liked it, subscribe wherever you listen. A like is nice. Ask the CEO of W. But a subscription is better.
Everyone purchased the technology. Almost nobody can demonstrate the financial return.
Across enterprise surveys, ninety-seven percent of executives claim to have deployed AI agents over the past year, with frontrunners managing multi-agent setups per knowledge worker. Yet fewer than a third report measurable returns from generative AI, under a quarter see payoff from autonomous agents, and seventy-three percent of CEOs cite operational stress from navigating the rollout. In Episode 15 of „Sarah’s Tech“, Sarah and I examine this widening split: is this systemic technology failure, or are we simply watching an economic rerun from the 1980s?
The Rerun: Robert Solow and the Productivity J-Curve
In July 1987, Nobel laureate Robert Solow summarized computing’s adoption lag in a single sentence: „You can see the computer age everywhere but in the productivity statistics.“
Corporate procurement teams spent a decade buying beige microcomputers while macro productivity numbers stayed completely flat. The measurable financial payoff arrived in the mid-1990s—roughly a decade late. The underlying mechanism is straightforward: buying hardware is the inexpensive, visible part. Redesigning organizational processes, retraining the workforce, and restructuring messy internal datasets represent the costly, invisible investments that weigh on margins for years.
Economists refer to this dynamic as the productivity J-curve. Initial capital expenditure books immediately as overhead with zero initial return, dragging down net performance before output eventually inflects upward. Seen through this lens, the sluggish enterprise ROI figures in 2026 reflect the trough of the J-curve rather than an outright dead end. For European organizations, methodical data remediation may not represent a structural delay—it could simply be the foundational half of the curve.
The Minitel Trap and the Modern „Dialer Moment“
Before the open internet arrived in European households, robust regional telematics networks already thrived: Prestel in the UK, BTX and Datex-J in Germany, and Minitel in France. Millions of French households used Minitel terminals for train timetables, banking, and messaging throughout the 1980s. Minitel’s legacy was not technical failure; it succeeded so thoroughly that abandoning it for the open web proved difficult. Whoever owns a functional, closed system transitions last.
The consumer internet ultimately broke through in markets like Germany not via revolutionary new infrastructure, but through distribution: 1&1 repurposed dialer software originally engineered for the BTX environment and distributed it on millions of magazine-mounted CDs. The future arrived through the old system’s distribution plumbing.
The AI sector faces a similar distribution bottleneck. Enterprise pilots remain heavily gated behind expensive consulting engagements. We put that distribution question to the test by reviewing eustella, a Viennese agent platform running open-weight models hosted on regional IONOS server clusters in Berlin and Frankfurt. While operational latency remains noticeable compared to centralized hyperscaler APIs, open-weight architectures provide an essential strategic guarantee: downloaded weight files cannot be revoked or turned off across borders.
What Empirical Stopwatch Trials Actually Reveal
Rigorous randomized controlled trials (RCTs) present a nuanced picture of workplace productivity:
Customer Operations: Large-scale trials involving over 5,000 support professionals recorded an average 14 percent increase in successfully resolved tickets per hour.
Software Engineering: Field experiments spanning thousands of developers at Microsoft, Accenture, and a Fortune 100 enterprise measured approximately 26 percent more completed tasks.
The Leveling Effect: Across multiple controlled studies, below-average performers and novices saw output surge by 30 to 40 percent, whereas top performers recorded minimal uplift or occasionally slowed down.
AI functions primarily as a leveler, not an elite performance multiplier. It elevates the operational floor while the ceiling remains stationary—meaning individual competitive advantages can rapidly compete away. Furthermore, testing reveals a severe jagged technological frontier: where tasks cross beyond model capabilities, error rates spike dramatically, often without clear visual warning to the user.
Where the Margin Lands for Small Enterprises
While large corporations face margin compression as baseline cost savings are competed away, smaller and mid-sized operators can use low-overhead automation to remove minimum-scale barriers. Five practical playbooks stand out:
The Long-Tail Task Backlog: Handling low-margin operational jobs where fixed administrative overhead previously rendered fulfillment unprofitable.
Vertical Micro-Software: Deep domain tooling tailored to specialized trades where the competitive moat is workflow knowledge rather than code complexity.
Succession Arbitrage: Acquiring succession-distressed small businesses trading at three to four times earnings, clearing operational backlog via agentic workflows instead of expanding headcount.
Proprietary Domain Data: Leveraging historical bidding records, project estimates, and proprietary win/loss ratios that frontier foundation models have never indexed.
Capacity Relief in Physical Trades: Automating back-office logistics to deploy scarce human technicians directly into high-value field work.
Evaluating State Initiatives: The Airbus vs. Gaia-X Framework
State-backed tech programs frequently draw immediate skepticism, but Europe’s industrial track record is nuanced. Evaluating initiatives like the €30 billion EuroHPC AI Gigafactories requires asking four baseline questions:
Artifact vs. Framework: Does the initiative manufacture a tangible product (Airbus) or convene working committees (Gaia-X)?
Committed Anchor Demand: Is volume secured upfront through guaranteed institutional buyers?
Ecosystem Alignment: Does the contributor roster include competing foreign vendors whose core commercial interest lies in slowing local autonomy?
Hardware vs. Horizon Bet: Concrete facilities carry thirty-year lifespans, while underlying compute accelerators turn obsolete in five.
Episode 15 Audio & Full Transcript
You can also subscribe and stream this episode directly on Apple Podcasts, Spotify, and via our direct RSS feed.
Sources & Empirical Research
Stopwatch Studies & Workplace Trials
Brynjolfsson, Li & Raymond:Generative AI at Work (NBER Working Paper 31161) –
Cui, Demirer, Jaffe, Musolff, Peng & Salz:The Effects of Generative AI on High-Skilled Work: Evidence from Three Field Experiments with Software Developers –
Dell’Acqua, McFowland, Mollick et al.:Navigating the Jagged Technological Frontier: Field Experimental Evidence on the Performance Effects of Generative AI –
Disclosure: Sarah Vejlby is a synthetic co-host. Her voice is AI-generated and disclosed in every episode in compliance with the EU AI Act’s Article 50 transparency requirements. Markus works in the web hosting sector (goneo Internet GmbH). This website uses no tracking pixels.
Feedback: If you operate an SME or manage engineering workflows: which of the five doors have you opened, and have measurable margins materialized on your balance sheet? Share your figures and operational setups with us at: feedback@experten-system.de.
Data wasn’t leaked from a sovereign cloud. It leaked from a third-party vendor.
That single detail from the summer of 2026 cuts straight through the marketing noise surrounding digital independence. You can construct ultra-secure data centers on domestic soil, but sovereignty inevitably ends where the external supply chain begins. In Episode 14, Sarah and I examine the fractures across the European tech ecosystem: from Schwarz Digits selling XM Cyber’s intellectual property to Texas, to a bumpy week in Neckarsulm, the European Commission’s new SEAL benchmark, and the €30 billion race for AI Gigafactories.
The Landlord Model: When Schwarz Digits Bets on US Security
In mid-July, the European cloud sector saw a major shift: CrowdStrike signed a binding agreement to acquire the intellectual property—including over 45 patents and core source code—of XM Cyber. This was the cybersecurity firm acquired by the Schwarz Group in 2021 for roughly $700 million to serve as the defensive backbone of STACKIT.
The deal structure is revealing: customer contracts and operational revenue stay with Schwarz, while the underlying intellectual property moves to Texas. In return, CrowdStrike’s Falcon platform lands natively on STACKIT racks with telemetry processed inside Europe, joined by a similar deployment from Zscaler.
From a CFO perspective, the logic holds up: proprietary security research at that depth is brutally capital-intensive, the market leader scales better, and local server racks get filled. Yet from a pure sovereignty perspective, it redefines the mission. Schwarz is pivoting away from the ideal of „we build the entire stack“ toward the posture of an enterprise landlord: we own the real estate and the concrete; the interior furnishings are leased.
The fact that this deal coincided with Lidl notifying online shop customers about a data incident at an external IT provider, alongside an operational hiccup at STACKIT, highlights the vulnerability of the landlord posture: the foundation is local, but the entities walking the corridors introduce external exposure.
Europe Builds a Ruler: Measuring Sovereignty with SEAL
Until recently, „sovereign cloud“ was largely an unverified marketing claim. With the European Commission’s Cloud Sovereignty Framework, procurement teams now have an objective measuring stick:
Heavy supply chain weighting: The supply chain criteria carries the single largest weight at 20 percent.
The SEAL Scale: Sovereignty Effectiveness Assurance Levels range from 0 to 4.
This framework directed real capital during the EU institutions‘ €180 million procurement round: STACKIT, Scaleway, and the consortium of Post Telecom, OVHcloud, and Clever Cloud all achieved SEAL-3.
Conversely, setups that merely place a local operating entity over a US hyperscaler stack capped out at SEAL-2. Corporate ownership within the EU is a prerequisite, but it is not sufficient on its own. Crucially, nobody reached SEAL-4. Level 4 mandates a verified, end-to-end European supply chain from the software layer down to the silicon. As long as every high-performance cloud stack relies on accelerators engineered in California and manufactured in Taiwan, SEAL-4 remains an unreachable standard. Sovereignty stops where semiconductor physics begins.
The Billionaire Test: Training Frontier AI in Europe
If a European enterprise or backer wants to train a proprietary large-scale foundation model strictly within European borders today, what are the actual options?
The Academic Route: Applying for allocations through EuroHPC systems (such as JUPITER or Alice Recoque). Invaluable for public research, but you receive an compute allotment, not dedicated infrastructure you control.
The Commercial Cloud: Providers like OVHcloud (noted as the sole European Challenger in Gartner’s Magic Quadrant for Cloud AI Infrastructure) and Scaleway offer viable platforms for inference and fine-tuning. However, provisioning tens of thousands of top-tier accelerators on a single low-latency fabric via credit card remains unavailable domestically.
The AI Gigafactories: The EuroHPC tender launched on July 30 targets up to seven facilities across member states, backed by €10 billion in public funding and over €20 billion in anticipated private capital.
To access frontier training capacity at home, you do not simply purchase instances—you submit proposals to a public-private partnership.
The Operational Takeaway: Sovereignty as an Insurance Policy
Organizations are not adopting European cloud providers because of feature parity or lower pricing. They are purchasing operational insurance against the CLOUD Act, jurisdictional friction, and unpredictable foreign policy shifts.
For standard workloads—virtual machines, object storage, Kubernetes deployments, managed relational databases—European providers deliver stable, cost-efficient infrastructure. Roughly 70 percent of a conventional enterprise IT footprint could migrate today without operational roadblocks. The remaining 30 percent—deep SAP migrations, legacy enterprise ERP setups, and complex managed AI pipelines—presents the actual migration bottleneck.
The rational approach for IT leadership in 2026 is deliberate workload tiering: isolate regulated, sensitive datasets on SEAL-3 European infrastructure, while keeping general operational workloads where feature depth and tooling ecosystems provide the highest leverage.
Join the Discussion
If you oversee cloud architecture or procurement: has an objective sovereignty framework like SEAL influenced your vendor evaluations, or does ecosystem lock-in dictate the final choice? What remains anchored to foreign hyperscalers because a viable European alternative is still missing?
Episode 13: A Ritual Without a Religion | How Europe Almost Killed the Cookie Banner — and Who Saved It
How many cookie banners did you click away today? Nobody knows—and that isn’t a failure of memory, it’s intentional system design. It is the most visible monument of European digital regulation: billions of clicks per day, 847 „partners who value your privacy,“ a cheerful „Accept All“ button, and a „Reject“ option buried beneath forty sliders and legitimate-interest toggles.
In this episode, we unpack the latest drama out of Brussels: Europe stood on the verge of killing the banner ritual with a single line of text—until Germany, France, Poland, and Google stepped in to pull the emergency brake.
The Rule That Almost Fixed the Web
Tucked inside the European Commission’s massive Digital Omnibus deregulation proposal was an unassuming measure: Article 88b. The idea was straightforward: make machine-readable privacy signals—set once in your browser, operating system, or consent agent—legally binding on websites.
Article 88b banned nothing. Tracking with genuine consent remained entirely lawful. It simply reallocated the transaction costs of the decision: moving the friction from exhausted users straight back onto ad-tech intermediaries.
Then came the compromise draft from the Cypriot Council presidency: Article 88b was struck entirely. Germany, France, and Poland pushed for the deletion, citing potential harm to the digital economy and a missing impact assessment—a procedural hurdle raised for the single consumer-facing rule, while twenty industry-facing deregulations sailed through without one. Google circulated warnings of a €40–50 billion hit to the digital ecosystem, and domestic publishing associations lined up behind them.
Does Advertising Actually Need Tracking? An Honest Fight
Beneath the backroom lobbying lies a fundamental disagreement, which Markus and Sarah debate head-on:
The Case for Context (Markus): Advertising ran on context for over a century before hyper-targeted surveillance arrived. When Dutch public broadcaster NPO/Ster killed third-party tracking in 2020, ad revenue jumped significantly—even as 90% of visitors opted out once refusing was made painless. Academic research shows behavioral targeting often yields only an approximate 4% revenue uplift for publishers. The surveillance layer primarily feeds ad-tech middlemen, not content creators.
The Reality of Attribution (Sarah): NPO succeeds with context because NPO owns premium content. A niche forum or hobby recipe site does not. Stripping behavioral signals doesn’t level the playing field; it accelerates the flight of capital directly into logged-in walled gardens like Google, Meta, and Amazon. Performance marketing runs on measurement, and privacy-preserving attribution remains deeply flawed.
The uncomfortable reveal hidden in Google’s €50 billion warning: if revenue collapses the moment saying „no“ takes a single click, the consent was never voluntary. A business model that survives only because refusal is exhausting has a legitimacy problem, not an efficiency problem.
Zoom Out: Labels, Margins, and the Delaware Route
The fate of Article 88b illustrates how European tech policy really operates. AI Act transparency labels survived because no major revenue model relies on keeping bots secret; binding privacy signals died because they threaten the margins of a €200 billion machine. Rules survive only when they don’t threaten incumbent cash flows.
If Europe wants true digital competitiveness, copying American deregulation or layering ever-thicker compliance rituals won’t solve it. The real path forward is copying Delaware: making Europe the fastest, simplest place on Earth to incorporate and scale through frameworks like EU Inc., rather than burning political capital shielding legacy ad trackers.
Key Takeaways
The Banner Is Leverage: The friction is the point. When opting out requires one click, 90% opt out.
88b Was True Deregulation: It eliminated friction for users by shifting the cost of asking back to the platform.
The Number Is the Confession: If making refusal easy costs billions, user consent was never genuinely given.
Win Like Delaware, Not a Lobby: Competitiveness comes from frictionless company creation and lean frameworks, not entrenched rent-seeking.
Sources & Further Reading
netzpolitik.org (24 June 2026): „Deutschland und Google wollen Cookie-Banner retten“ — Leaked Council records and member-state positions.
noyb (23 June 2026): „EU Member States (and Google) suddenly want to keep cookie banners!“ — Analysis by Max Schrems.
BVDW (March 2026): Industry statement on the Digital Omnibus.
Brave / Johnny Ryan (July 2020): Six-month NPO/Ster case study on contextual ad revenue.
Marotta, Abhishek & Acquisti (2019):Online Tracking and Publishers‘ Revenues: An Empirical Analysis.
European Commission (18 March 2026): EU Inc. 28th regime proposal.
Disclosure: Sarah Vejlby is a synthetic co-host with an AI-generated voice, disclosed in compliance with the EU AI Act. markus.technology operates without tracking pixels.
Join the Discussion: Do you buy ads, sell inventory, or run commercial web infrastructure? Would binding privacy signals have broken your unit economics or simplified your stack? Send your raw numbers and views to feedback@experten-system.de.
Companion piece to Episode 12 of Sarah’s Tech. The episode tells three stories. This page holds the figures, dates and sources behind them — and the three levers we ended on. Where numbers are contested or approximate, they’re marked as such.
The pattern in one sentence: Europe won the device three times and lost the layer underneath three times — the standard, the network, the operating system. Round four is being assigned right now.
Loss One: The Standard (1981–2023)
In 1981 the BBC set out to find one official machine for its Computer Literacy Project. Two Cambridge companies competed: Sinclair Research, and Acorn Computers — founded by Chris Curry, who had worked for Clive Sinclair before leaving to start his own firm. Acorn won. The BBC Micro sold around 1.5 million units and taught a generation of British children to program.
Then the standard moved elsewhere. The IBM PC and Microsoft’s operating system became the platform everyone else built on and around, and within a few years the European home computer industry was gone: Sinclair sold to Amstrad in 1986, Acorn faded, Philips and Olivetti exited.
Meanwhile the BBC Micro’s profits had quietly funded an in-house chip project. Sophie Wilson designed the instruction set, Steve Furber the hardware; first working silicon came in 1985. In 1990 it was spun out as a joint venture between Acorn, VLSI Technology and Apple, which needed a low-power processor for the Newton. The name: Acorn RISC Machine. Later, Advanced RISC Machines. Today, Arm.
What happened to it since:
Year
Event
1998
IPO in London and on Nasdaq
2016
SoftBank acquires Arm for about $32bn (£24.3bn)
2020–2022
Nvidia’s ~$40bn acquisition attempt collapses under regulatory pressure
2023
UK government campaigns for a London listing; Arm declines
Sept 2023
IPO on Nasdaq at $51/share, ~$54.5bn valuation, ~$4.87bn raised; SoftBank retains ~90%
2026
Market value around $280bn — Europe’s second most valuable tech company
The mechanism. Europe didn’t lose the customer. British children loved those machines. It lost the standard — the layer everyone else has to build on. Once that’s gone, the best available outcome is to be a brilliant supplier to someone else’s platform. Arm is exactly that: its designs are in roughly 99% of smartphones, and not one of those is a European platform.
The irony. Apple co-founded Arm in 1990. Apple silicon runs on Arm architecture today, and the returns flow to Cupertino and Tokyo.
Loss Two: The Network (1997–2008)
Disclosure: I worked at Lycos Europe during this period. The figures below are from public sources, not from anything internal.
Lycos Europe was founded in 1997 as a joint venture between Bertelsmann and Lycos Inc. In March 2000 it went public on Frankfurt’s Neuer Markt, raising about €612 million at a valuation near €5.5 billion.
Worth pausing on that exchange for a moment: for roughly six years, Germany had a functioning growth market with hundreds of tech listings and enthusiastic retail investors. Anyone claiming Germans are congenitally afraid of equities should explain the year 2000.
Then the shopping: Lycos Europe acquired Sweden’s Spray Network for roughly $570 million in cash and shares — including the Spraydate community and France’s Caramail — alongside Jubii in Denmark, Fireball in Germany, MultiMania in France and the Pangora shopping engine. This was European consumer internet, bought with European capital, run from Europe.
It wasn’t acquired by an American company. It dissolved. Spray went back to a Swedish publisher in 2006; on 26 November 2008 Lycos Europe announced it would wind down and sell what remained.
And it wasn’t alone in the landscape. Europe had LunarStorm in Sweden — among the world’s first social networks — plus StudiVZ in Germany, Netlog in Belgium and Skyrock in France. All of it is gone.
The mechanism. A portal is not a network. Lycos Europe bought reach: visitors, page views, mail accounts. Reach is rented attention — it walks out the door whenever something better appears. A network owns the connections between users: every added friend made leaving harder and joining more valuable for the next person. Hundreds of millions went into the thing that doesn’t compound while a dorm room built the thing that does.
Loss Three: The Operating System (1998–2013)
Nokia at its peak sold roughly four in ten mobile phones worldwide — the strongest consumer technology brand Europe has produced. The iPhone arrived in 2007, Android in 2008.
The part usually skipped: Nokia’s hardware remained excellent for years. What collapsed was Symbian, against two platforms with app stores. Developers followed users, users followed apps, and that loop compounded away from Espoo. By 2013 the phone business went to Microsoft. Nokia survives today as a network equipment supplier — a supplier again.
The Diagnosis That Doesn’t Hold
The intuitive explanation is that Europeans are somehow technology-averse. The adoption data says otherwise: European consumers embraced home computers, Nokia phones, social networks, streaming and contactless payments — often ahead of the US. What is larger in Europe is distrust of the institutions behind the technology, not of the devices themselves.
The stronger explanation is fragmentation. An American consumer startup gets 330 million people, one language and one legal system on day one. A European one gets 24 languages and 27 rulebooks. B2B tolerates that — English contracts, few large customers, long sales cycles. Consumer platforms live on cheap, fast scaling, which is exactly where fragmentation bites hardest.
But Sweden breaks it. Ten million people, an equity culture, high founder density — Spray, LunarStorm, Skype, King, Spotify, Klarna. If fragmentation were the whole answer, Sweden shouldn’t exist. And yet Spotify and Klarna both listed in New York. Neither theory survives contact with Stockholm. Which is where the levers come in.
Round Four Is Running Now
Same structure, new layer. Europe is again excellent below the platform: ASML makes the lithography machines, Schneider Electric powers the data centres, IQM builds quantum processors. The AI platform layer — models, assistants, the interfaces everyone will build on — is being set elsewhere. Europe’s most serious attempt is Mistral in Paris, which is private; the only public-market route into it runs through ASML’s €1.7bn stake.
The counter-move is institutional rather than entrepreneurial so far: openDesk, the Sovereign Tech Agency, public-code procurement — Europe’s first organised attempt to hold a layer instead of building devices. Whether that’s enough is an open question. (We covered it in Episode 10.)
Three Levers
1. Capital depth
Companies list where retirement savings sit in equities. That’s the unglamorous core. Europe’s savings are enormous and largely parked in bank deposits.
The proof that this is fixable is inside Europe: Sweden’s ISK investment account and its premium pension pushed ordinary savers into equities, and Stockholm has seen more IPOs over the past decade than Frankfurt and Paris combined.
Two levers travel with it. Dual-class shares, because founders who would lose control by listing at home list elsewhere instead. And index gravity, because passive money follows the indices that follow depth.
Resolving the Sweden paradox: national capital culture is necessary and not sufficient. A very good lake is still not an ocean — Klarna’s IPO needed more depth than any single European market offers. Which is why the answer is one European pool, not 27 national fixes, and why the Savings and Investments Union matters however bureaucratic it sounds. In June 2026 member states agreed a position on reforming the pan-European pension product; the Commission is pushing tax-favoured investment accounts — essentially the Swedish account, exported.
2. Staying power
Employee equity. Germany taxed stock options at grant for years — tax due on paper wealth before a single share could be sold. Dry income. Largely fixed in 2024: taxation is now deferred, up to fifteen years or until sale. Real progress, still patchwork — every member state does it differently, and virtual options, the workaround most startups use, are taxed as salary at rates up to 45%.
The legal shell. Klarna became a UK plc; Wise’s holding sits in Jersey. Not patriotism, convenience: no European form was as familiar to global investors. In March 2026 the Commission proposed the EU Inc. — a 28th regime, one European company form alongside the 27 national ones, with digital registration, EU-wide validity, and a single tax treatment for employee stock. Political agreement is targeted for end-2026; realistically the first EU Inc. gets incorporated around 2028.
Anchor customers. The least romantic and probably most effective lever: a company stays where its revenue lives. Public procurement — openDesk, standardised open-source contracts, the state as first big customer — creates a revenue base nobody walks away from. Patriotism doesn’t retain companies. Purchase orders do.
3. Open boards
The honest answer begins with a renunciation: Europe will not get its Google by building a more privacy-friendly Google. Rebuilding a platform that already won means burning capital against network effects that have already compounded.
Platform battles are winnable only while the board is still open. That’s the actual lesson of all three stories — Acorn lost a board IBM had already set; Facebook won one that was still empty.
Boards that are open right now:
Industrial AI — the layer where factories meet models doesn’t exist yet, and Europe owns the factories.
Defence technology — being assigned now, and for sovereignty reasons not easily American-owned. Helsing’s ~$18bn valuation reflects exactly that.
Energy systems — grid, storage and demand orchestration as software.
Quantum — IQM sells machines; the software layer above them is unclaimed.
The precondition for all of them is scale at home: a company form, a capital pool and procurement rules that make 450 million customers behave like one market instead of 27. Since the Draghi report in 2024 that agenda has moved from speeches into legislative machinery.
The Deadline
Round four doesn’t wait for the trilogue calendar. The AI platform layer is being assigned now — and on current form, by companies listed on Nasdaq.
The encouraging part, if you want one: this layer isn’t set in a keynote. It’s set in a million procurement and architecture decisions. Every agency choosing between a US model API and open weights, every hoster deciding whose inference to resell, casts a small vote on where it settles.
Question back to you: which of the three levers would change your business first — the capital, the company form, or the anchor customer? And if you were there for one of the three lost platforms: what did it look like from the inside? feedback@experten-system.de
Further Reading
Primary sources where they exist, and the best archives where they don’t. The episode keeps numbers deliberately thin; this is where to check them.
Loss one — Acorn, the BBC Micro and Arm
BBC Computer Literacy Project Archive — the BBC’s own archive: 146 original programmes plus 121 related ones, broken into searchable clips. The history section covers how Acorn won the contract with the Proton prototype, and notes that the Acorn team went on to develop the RISC chips now in mobile phones.
Arm Holdings Form F-1 (SEC, 2023) — the IPO prospectus itself, including the corporate reorganisation into Arm Holdings plc. Long, but the risk factors section is the most candid document about Arm’s dependencies you will find.
Loss two — Lycos Europe, Spray and the Neuer Markt
No canonical archive exists for this one, which is part of the point: a company that dissolved leaves fewer traces than a company that was bought. The March 2000 Neuer Markt prospectus, the Spray Network acquisition announcement and the 26 November 2008 wind-down statement are best found through newspaper archives and company-register records rather than a single web page. If you have a primary document from that period, send it — it belongs in this list.
Loss three — Nokia and Symbian
Covered exhaustively in business-school literature; start with Nokia’s own annual reports from 2007 to 2013 for the gap between hardware quality and platform share.
The levers
EU Inc. — European Commission announcement, 18 March 2026 — the 28th regime: incorporation within 48 hours, under €100, no minimum share capital, with the Commission calling on Parliament and Council to agree by the end of 2026.
The proposal itself (PDF) — COM(2026) 321 final, for anyone who wants the legal text rather than the summary.
the28thregime.eu — an independent tracker of the legislative file, useful because this is a moving target: the Parliament’s JURI draft report of 29 June 2026 alone runs to 151 pages and 246 amendments.
The Draghi report on EU competitiveness — published 9 September 2024, the document that moved this agenda from speeches into legislative machinery. Part A is 65 pages; Part B is the 328-page analysis.
The counter-move, from Episode 10
Sovereign Tech Agency — public investment in the open digital infrastructure everything else runs on.
openDesk — the open source workplace for the public sector, and the clearest working example of the state as anchor customer.
Links checked August 2026. The EU Inc. and Savings and Investments Union files are live legislative processes — verify the current status before quoting either.
Sources: figures on Arm’s ownership and listings from company and press reporting; Lycos Europe IPO, acquisition and wind-down figures from contemporaneous reporting; EU Inc. and Savings and Investments Union status as of mid-2026 — both are ongoing legislative processes, so check for newer developments before quoting them.
The companion piece to the podcast episode11 of Sarah’s tech
This is a thought experiment, not investment advice. We picked companies for what they tell us about Europe’s tech economy — not for their prospects as investments. Valuations are approximate (Q2/Q3 2026, mixed USD/EUR as reported); WKNs are German securities identifiers for readers who want to look companies up on German finance portals.
The one number to remember: the three largest positions in this list — ASML, ARM and SAP — are worth more than the other forty combined. One of the three trades on Nasdaq.
Basket 1: Semiconductors, Software & IT Services
Company
HQ
Listed
WKN
Mkt Cap
What they do
ASML
Veldhoven, NL
Euronext Amsterdam + Nasdaq
A1J4U4
$678B
Lithography machines for chipmaking, ~90% market share. Every advanced chip on earth passes through an ASML machine.
ARM Holdings
Cambridge, UK
Nasdaq
A3EUCF*
$280B
CPU architecture licensed into 99% of smartphones. Owned by SoftBank. Europe’s second-most-valuable tech firm — listed in New York.
SAP
Walldorf, DE
Xetra
716460
$182B
Enterprise software (ERP). Europe’s largest software company; runs the back office of most global corporations.
Infineon
Munich, DE
Xetra
623100
$100B
Power and automotive semiconductors; market leader in chips that manage electricity.
NXP
Eindhoven, NL
Nasdaq
A1C5WJ*
$68B
Automotive and secure-connectivity chips. Dutch HQ, US listing.
STMicroelectronics
Geneva, CH (FR/IT)
Euronext Paris/Milan
893438
$60B
Sensors, microcontrollers, power chips — a Franco-Italian merger from 1987.
Nokia
Espoo, FI
Nasdaq Helsinki
870737
$58B
Telecom network equipment and patents. The former consumer giant, reborn as infrastructure.
ASM International
Almere, NL
Euronext Amsterdam
972092*
$52B
Atomic layer deposition equipment — another Dutch chokepoint in chipmaking.
Ericsson
Stockholm, SE
Nasdaq Stockholm
850001
$33B
Mobile network equipment; supplies the world’s 5G carriers.
Dassault Systèmes
Vélizy, FR
Euronext Paris
A0DPPB*
$28B
3D design and product-lifecycle software (CATIA); Boeing and VW design on it.
Capgemini
Paris, FR
Euronext Paris
869858
—
IT consulting and systems integration at global scale.
Reply
Turin, IT
Borsa Italiana
A2G9K9
~€3.6B
Italian IT services network focused on cloud, AI and digital transformation.
Bechtle
Neckarsulm, DE
Xetra
515870
—
IT systems house for the German Mittelstand and public sector.
Indra Sistemas
Madrid, ES
BME Madrid
A0ETNA*
$9.8B
Spanish defence electronics and IT — air traffic, elections, transport systems.
Basket 2: Cloud & Digital Infrastructure
Company
HQ
Listed
WKN
Mkt Cap
What they do
Nebius Group
Amsterdam, NL
Nasdaq
A1JGSL
$44B
AI cloud („neocloud“) carved out of Yandex; Microsoft and Meta among its customers. Amsterdam HQ, New York listing, complicated past.
Schneider Electric
Rueil, FR
Euronext Paris
860180
—
Energy management and data-centre power — the quiet winner of the AI build-out.
IONOS
Montabaur, DE
Xetra
A3E00M
~€4.2B
Europe’s largest web host (11M+ domains), cloud for SMEs. Free float ~12%; United Internet holds the rest. (Disclosure: the author works for a competitor.)
OVH Groupe
Roubaix, FR
Euronext Paris
A3C45N
~€1.8B
France’s sovereign-cloud champion; builds its own servers and data centres. Worth roughly 1/1000th of a US hyperscaler.
Quest Holdings
Athens, GR
Athens SE
A1XA84
~€0.8B
Greece’s digital conglomerate: IT integration, ACS courier network, electronics retail.
AROBS Transilvania
Cluj, RO
Bucharest SE
A3EK2B
micro
Romanian software house (automotive, telematics) — proof the talent exists; the listing is barely tradable from Western Europe.
Europe’s only industrial-robotics world player; electrification and automation.
Hexagon
Stockholm, SE
Nasdaq Stockholm
A1H4Y3*
$22B
Sensors and measurement software for factories and mines — the overlooked Swede.
Kion Group
Frankfurt, DE
Xetra
KGX888
—
Forklifts and warehouse automation. Largest shareholder: China’s Weichai Power (~47%).
AutoStore
Nedre Vats, NO
Oslo Børs
A3C5A3
~€4B
Cube-storage warehouse robots. Norwegian operations — registered in Bermuda.
Kardex
Zurich, CH
SIX
A0RMWK
~€2B
Automated storage and retrieval systems.
Dürr
Bietigheim, DE
Xetra
556520
—
Paint-shop robots for the car industry; world leader in its niche.
Jungheinrich (pref.)
Hamburg, DE
Xetra
621993
—
Intralogistics and warehouse trucks.
Basler
Ahrensburg, DE
Xetra
510200
—
Industrial cameras — machine vision for robots.
Basket 4: E-Commerce, Platforms & Payments
Company
HQ
Listed
WKN
Mkt Cap
What they do
Prosus
Amsterdam, NL
Euronext Amsterdam
A2PRDK*
$101B
Consumer-internet holding; ~80% of value is a stake in China’s Tencent.
Spotify
Stockholm, SE
NYSE
A2JEGN
$98B
Music streaming, 750M users. Swedish product, Luxembourg legal shell, New York listing.
Adyen
Amsterdam, NL
Euronext Amsterdam
A2JNF4
$31B
Payment platform for global merchants; one of the few that stayed home.
Amadeus IT
Madrid, ES
BME Madrid
A1CXN0
$25B
The booking backbone of global travel — a genuine European platform monopoly.
Delivery Hero
Berlin, DE
Xetra
A2E4K4
$13B
Food and quick-commerce delivery across 70 countries.
Wise
London, UK
Nasdaq (2nd listing LSE)
A3EWWA*
$13B
Cross-border payments. Founded by Estonians, built in London, incorporated in Jersey — primary listing moved to Nasdaq in May 2026.
Allegro
Poznań, PL
GPW Warsaw
A2QEGF
$12B
Poland’s dominant marketplace (~45–50% of e-commerce GMV); Luxembourg holding.
Klarna
Stockholm, SE
NYSE
A414N7
—
Buy-now-pay-later, 111M users. Swedish bank licence, UK plc, NYSE listing since Sept 2025.
Zalando
Berlin, DE
Xetra
ZAL111
—
Europe’s largest fashion platform.
Ocado
Hatfield, UK
LSE
A1C2GZ
~£1.5B
Started as an online grocer; now earns its keep selling warehouse robotics.
Redcare Pharmacy
Sevenum, NL
Xetra
A2AR94
~€1.3B
Online pharmacy (ex Shop Apotheke) for the DACH market and beyond.
HelloFresh
Berlin, DE
Xetra
A16140
—
Meal-kit pioneer.
Auto1
Berlin, DE
Xetra
A2LQ88
—
Wholesale and retail used-car platform.
Basket 5: Quantum & AI
Company
HQ
Listed
WKN
Mkt Cap
What they do
IQM Quantum Computers
Espoo, FI + Munich
Nasdaq (via SPAC, 2 July 2026)
—
~$2.5B
Europe’s first listed quantum company: 23 full-stack superconducting systems sold, customers incl. Leibniz Supercomputing Centre. Helsinki second listing announced.
(investable AI proxies)
SAP, IONOS, Nebius, Schneider, Hexagon, Siemens, plus the chip chain above. There is no listed European AI lab.
The Bench: Built in Europe, Not Buyable in Europe
Private companies — valuations from funding rounds, not markets:
Mistral AI (Paris) — ~$14–20B. Europe’s flagship AI lab. IPO announced, no date. ASML invested €1.7B — the only public-market route to Mistral runs through a lithography company.
Celonis (Munich) — $13B. Process mining.
ElevenLabs (London/Warsaw) — $11B. Voice AI. (Full disclosure: this podcast’s co-host runs on it.)
Vinted (Vilnius) — $9.3B. The Baltic answer: the region’s biggest tech company has no ticker at all.
What the list actually shows
Europe’s top layer is suppliers, not platforms. ASML, ARM, Infineon, ASM, Besi — the shovels of the digital gold rush. Consumer attention (search, social, OS, app stores) is entirely absent.
The younger and faster a European tech company, the more likely it lists in New York. Spotify, Klarna, Wise, ARM, IQM, Nebius. The pattern holds across fintech, media, quantum and cloud.
„European“ is a legal fiction the moment you look closely. Swedish operations, UK plc, NYSE ticker (Klarna). Norwegian robots, Bermuda registration (AutoStore). Estonian founders, Jersey holding, Nasdaq listing (Wise).
A European tech ETF therefore doesn’t measure where Europe builds technology. It measures where Europe owns it. Those are different maps.
WKNs marked * were compiled from standard identifier databases and should be verified. Not investment advice.
Sweden’s Cash Law, Stripe’s $53bn Bid, and the Digital Euro
Sarahs Tech, episode 9. My co-host Sarah is an AI voice — the research, the arguments and the responsibility here are mine. There’s more on why the show works that way over here.
I recorded this one because of a coincidence I couldn’t shake. In a single week in July, three payment stories broke that everyone treated as separate. Sweden — the most cashless country in Europe — passed a law forcing supermarkets to take cash again. Stripe bid fifty-three billion dollars for PayPal. And the European Parliament quietly sent the digital euro into trilogue.
(Click to listen on Apple Podcast page)
Read individually, they’re three headlines. Read together, they’re one question, asked from three directions: who owns the checkout? Who controls the rails your money actually runs on. That’s the whole episode.
Sweden hit the brakes — and it wasn’t nostalgia
Here’s what got me. Only five percent of Swedes paid cash for their last in-store purchase. Five percent. This is the country that put card readers in churches. And since the first of July, grocery stores and pharmacies there are legally required to accept cash again.
The reasoning isn’t sentimental, it’s engineering. After 180-plus outages at their main payment app in one year, and DDoS attacks knocking out the country’s core digital ID, the Riksbank drew a conclusion any of us who run infrastructure already know in our bones: a system with only one mode isn’t a system. It’s a single point of failure. Sweden didn’t abandon digital. It added a fallback layer. That distinction runs through everything that follows.
What Stripe is actually buying
PayPal is down about ninety percent from its 2021 peak. So why would Stripe pay fifty-three billion for it? Because Stripe isn’t buying the technology — it’s buying the relationship. Stripe owns the merchant side, the checkout, the developer API. What it has never had is a consumer wallet that hundreds of millions of people opened voluntarily. PayPal is exactly that.
For anyone here who runs a shop or builds checkout software, that’s the part worth sitting with. When the infrastructure behind the checkout and the customer-facing wallet end up in one hand, you eventually negotiate fees, terms and data access with a counterpart you can’t route around. And in this episode, Sarah pushes me on whether „European dependency“ is a real risk or just a talking point. I don’t let myself off the hook easily.
The digital euro: what it is, and what it isn’t
This is where most coverage falls apart, so we slowed right down. The digital euro is central bank money — the same currency as the cash in your pocket, in digital form. Not a cryptocurrency, not a new currency, not a coin that swings in value. The key difference from the balance in your bank account is the counterparty: a deposit is a claim against your bank, the digital euro would be a claim against the ECB itself.
Two things I want on the record, because I keep seeing them mangled. First: nothing is decided. The July 9th vote was a negotiating mandate, not a regulation, and even after the law passes the ECB alone decides whether to issue. Second: that famous three-thousand-euro holding limit is a discussion figure, not law — and its purpose is banking statics, not surveillance. Without a cap, deposits could drain from commercial banks into central bank money within hours during a crisis. The limit exists to prevent a design flaw, not to restrict you.
We also take the hard questions head-on: surveillance, cash abolition, programmability. There’s one objection I genuinely couldn’t argue away, and I say so on air rather than pretend otherwise.
Europe isn’t building the next PayPal. Europe is building the ground a European PayPal could actually stand on.
Could Europe build its own SWIFT?
Sarah set this up as the big ambitious question — and then dismantled the premise, which is exactly why I wanted her to ask it. SWIFT settles no money at all; it’s a messaging network. And it’s already a Belgian cooperative. Europe owns SWIFT. The real dependency sits somewhere else entirely — at the register and in the online checkout, and increasingly in dollar-denominated stablecoins.
The honest answer comes in three layers. The retail euro is built small on purpose — it’s defense, not an export product. The genuine international ambition lives in the wholesale projects almost nobody talks about, Pontes and Appia, one of which starts piloting this quarter. And reserve-currency status? That depends on the depth of capital markets, not on code. Technology can open the door. Politics has to walk through it.
What you can do with this
If your checkout runs on exactly one payment provider, you’ve got the Sweden problem in miniature — one mode, no failover. Worth an honest look regardless of how the Stripe deal plays out.
Watch the trilogue through the end of 2026. That’s when we’ll know whether the 2029 timeline for the digital euro holds. If you build shop or POS software, the planned acceptance obligation is your planning signal — a topic for the roadmap after next, not the next one.
Keep half an eye on Pontes and Appia. If settlement in central bank money becomes standard, the interesting work usually appears one layer below the hype.
Chapters
00:00 — Cold open & full transparency
01:55 — Sweden backpedals
04:55 — The $53 billion bid
07:50 — Data sovereignty, made concrete
10:15 — What the digital euro is (and isn’t)
16:45 — The SWIFT question
23:15 — Practice & outro
Listen & subscribe
Episode 9 is out now. If it’s useful, the best thing you can do is subscribe wherever you listen — it’s how the show finds the next few hundred people who care about this stuff. And if you run a checkout with one provider, are building software that might have to handle a digital euro by 2029, or simply think the whole project is a mistake, I want to hear it. Reply, or drop me a note — anonymously if you prefer. The sharpest responses tend to end up in a future episode.
European Parliament: the 9 July 2026 plenary confirmed the negotiating mandate (416 in favour, 169 against, 22 abstentions); rapporteur Fernando Navarrete Rojas leads Parliament’s team. Search „digital euro“ in the newsroom for the statement.
What Bosses Believe, What Builders Know (Sarah’s Tech S1·E08)
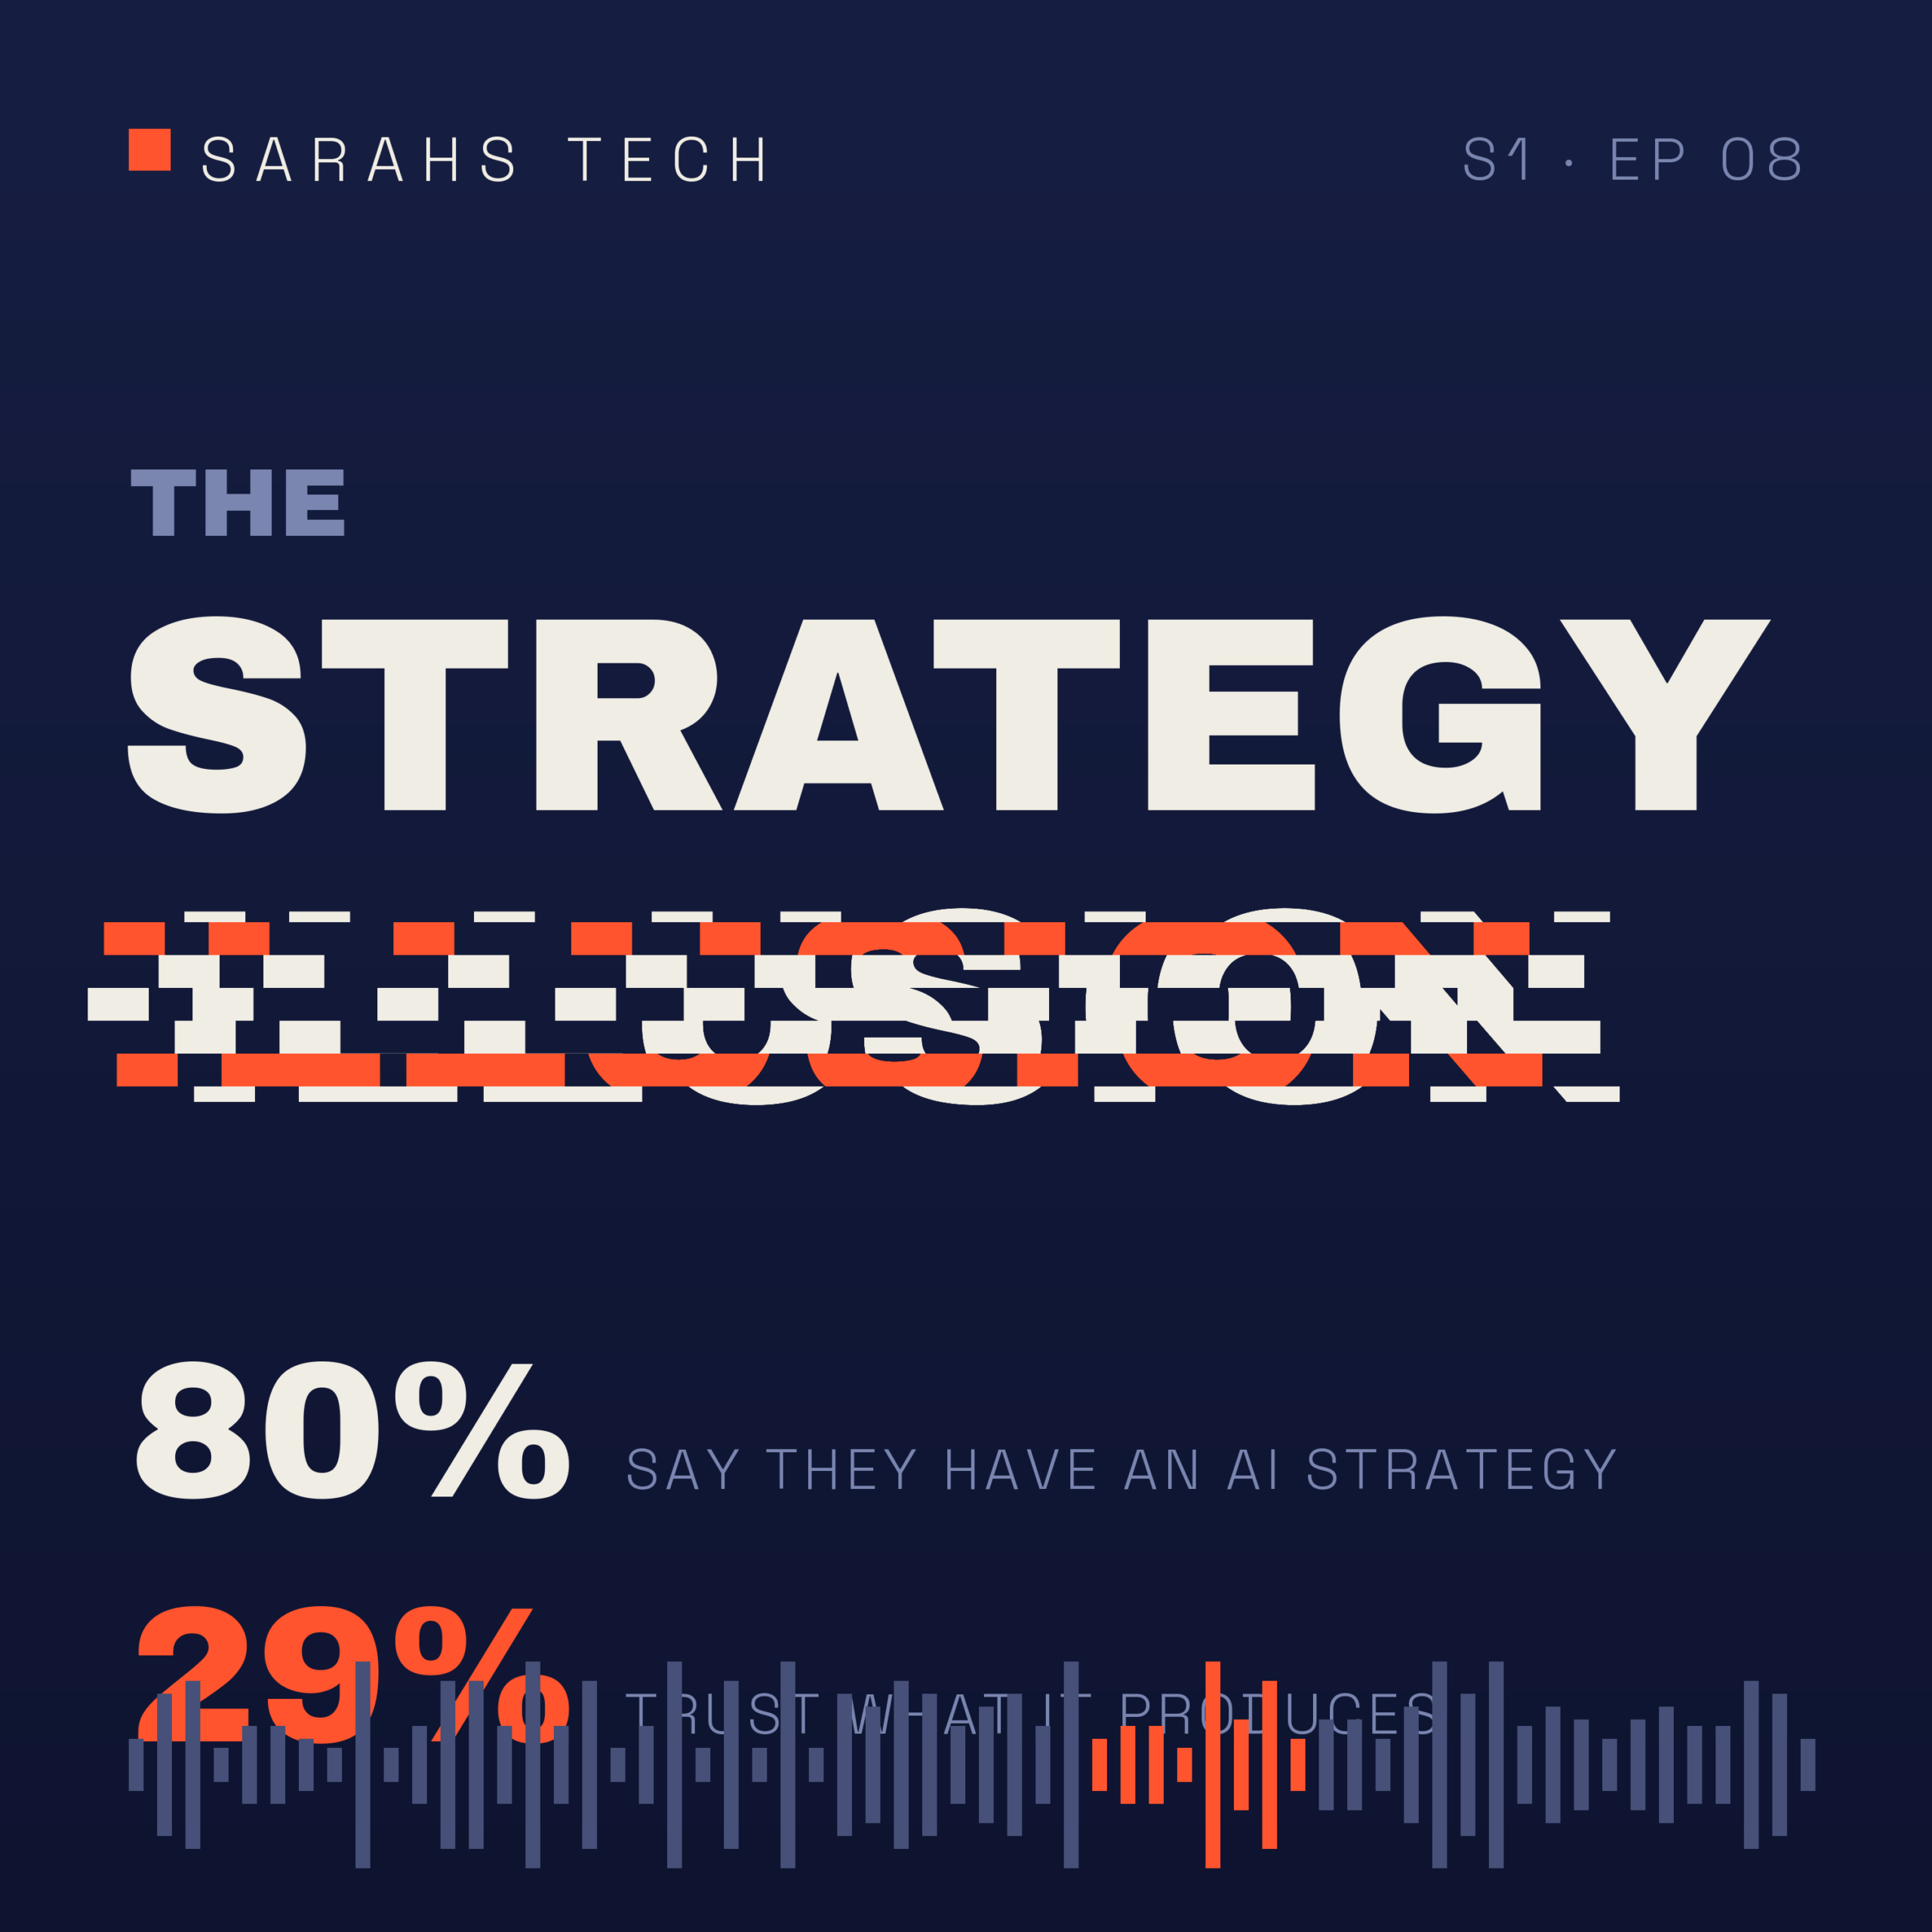
80% of European industrial companies say they have an AI strategy. The developers who build the actual products trust AI output at 29%. Someone here is wrong — or, more uncomfortably, nobody is.
The new episode of Sarahs Tech is out, and it lives in the gap between those two numbers.
What this episode is about
We start with a bet. Before the jingle, Markus claims AI makes him about twenty percent faster. Would he put money on that? He shouldn’t. A research lab recently put a stopwatch on experienced developers working on real tasks — randomized, screens recorded, time measured. With AI, they were 19% slower. And afterwards, they estimated they had been 20% faster. That forty-point gap between feeling and reality is the theme of the whole episode.
From there, we take the elevator through European tech, floor by floor:
The status report from the wall. The EU AI Act’s transparency rules go live on August 2nd — and no, the „delay“ you read about doesn’t apply to you. The high-risk rules were pushed to 2027 and 2028; the labeling duties arrive on time. There are official EU icons now („AI GENERATED“ / „AI MODIFIED“), the label belongs inside the content rather than the caption, and unlike NIS2, anyone with a smartphone can spot a violation. We walk through what that means for marketing teams, agencies, publishers and podcasters — including one detail that surprised us: AI translation counts as content that needs marking.
The view from the top floor. A fresh survey asked 800 industrial decision-makers across eight European countries about digital strategy. The results look great. Suspiciously great: 88% have a digitalization strategy, 80% an AI strategy, 92% plan new digital business models within three years. We do the source criticism this study deserves — and then dig out the three findings that are genuinely revealing. Data sovereignty ranks only third among infrastructure priorities, behind security and cost. Only half of decision-makers see Europe as one unified market — and the country that believes in it most is Germany, while France believes in it least. Germany dreams the European dream. Alone.
The view from the workbench. The people actually building the products tell a different story. Developer adoption of AI tools is basically done (84%), but trust in the output collapsed to 29% — and the most experienced developers are the most skeptical. Two thirds name the same frustration: solutions that are almost right, but not quite. Meanwhile, DACH freelancers have quietly turned pragmatic: more than half use AI daily, 18% already report lower hourly rates because of it, and 44% don’t tell their clients at all. That silence gets expensive after August 2nd.
We close with a practical four-step checklist to get ready for the deadline — inventory, review workflow, labels, contracts — plus one piece of advice for freelancers that has survived every technology Markus has worked with since 2000: say it before they ask.
One more thing
We open this episode with a confession. Sarah — the host this show is named after — doesn’t exist. Her voice is synthetic, her personality is a writing device, and everything she says is researched, written and editorially owned by Markus. From August 2nd, that disclosure becomes a legal requirement. We’re just early. Full concept behind Sarah: markus.technology/sarah
Listen now
🎧 Listen to the episode on your favorite podcast app or directly here:
The Bug Was Always There | PHP2Shell, Jensen's Robot Ducks, and Why Johanna Gets Paid Less –
Sarah's Tech
Episode 23: The Bug Was Always ThereA flaw in PHP itself sent half of Europe's public websites offline. It had been spotted in 2024, paid for with German public money, and then nobody fixed it. Sarah and Markus argue about whether the shutdowns were panic or honesty, follow the money from Jensen Huang's billions to a foundation asking for donations, and hear from the man who started it all: Rasmus Lerdorf, in original audio from 2017. In this episode: 00:00 Cold Open and Welcome. Hundreds of broken requests against our own website, and this week the noise has a name. Half of Europe switches off its websites. Is this what European sovereignty looks like? 02:10 Housekeeping. Switzerland puts 63 percent of its venture capital into deep tech, but 88 percent of the money in big rounds comes from abroad and pension funds barely invest. Europe pays for the research, someone else cashes in. Then France: half a million people on the streets, mobilised online, and a viral riot video that turned out to be from 2020. 04:44 On the Record. Jensen Huang's Europe tour: fourteen startups in a week, nearly ten billion dollars in a year, Nvidia behind ten to fifteen percent of European startup funding. Doctolib bought at a discount, open models on closed chips, and four Microducks from Bordeaux, owned by Hugging Face, which Nvidia has agreed to buy. Meanwhile in Malmö: the Matrix Conference. Sovereignty doesn't come with a keynote. It comes with maintainers. 10:52 PHP2Shell: What Broke. Not a WordPress bug, but PHP itself. A request runs out of memory, PHP cleans up badly, and the next request finds the master key under the pillow. Why mod_php is the worst case. 13:14 PHP2Shell: The Timeline. A 2024 audit funded by Germany's Sovereign Tech Agency, AI-assisted findings in August 2026, a leak, a broken embargo, and an exploit attempt on an Amazon honeypot four days before disclosure. Why the patch itself is a map. 18:23 Switch It Off? Charité, Mainz, DigiD, Final Fantasy XIV and the Berlin police telling citizens to dial 110. Markus says many overdid it, AWS only warned. Sarah: AWS doesn't run your PHP, a shared hoster does. They meet halfway: the shutdown was the symptom of not knowing your own inventory. Plus: how AI made an old flaw cheap to exploit. 19:51 Hall of European Tech: Rasmus Lerdorf. Born in Greenland, raised in Denmark and Canada. In 1995 he publishes "Personal Home Page Tools" to see who reads his CV. From Zend to HHVM to PHP 7. With original audio from Markus's 2017 interview in Dortmund: no grand plans, just a useful tool, and the principle to make things easy. 23:52 Who Pays for the Foundation? "Not my employees": how PHP development is funded. Around 200,000 euros of public money against Nvidia's billions. Every hoster earns money with PHP. If you sell PHP, you should pay into PHP. 26:59 What You Should Do Now. The fixed versions, the right question for your hoster, Docker images, devices with web interfaces, old systems, and why a patch doesn't remove an attacker who's already in. And why our European podcast site was protected by an American firewall. 28:51 Johan and Johanna. In a VR study, a female AI assistant got 10.25 percent less than a male one for the same work, and the male one seemed more human. Sarah asks Markus why he made her a woman. Then the bill: 200 euros per episode, and nobody on the show gets paid. Followed by our closing song "Both Sides Of The Wire", full length at sarahs-tech.eu/?seite=song. Newsletter: Context Window. What we talked about, what we cut, what's coming. Subscribe at sarahs-tech.eu. Key Takeaways: The Bug Was Always There: An audit found the memory flaw in 2024. AI didn't discover a new bug, it made an old one cheap to exploit. The Shutdown Was the Symptom: Switching off is honest when you can't patch. Needing a blackout to patch means you don't know what runs on your servers. Not Comparable: AWS and Shared Hosting: A cloud provider can't switch off PHP it doesn't operate. A shared hoster runs it for thousands of customers and has to act. Waiting It Out Is Now the Attacker's Strategy: Millions of PHP installations run on unsupported versions. A patch is read and turned into an exploit within hours. Who Sells PHP Should Pay Into PHP: The web's foundation runs on donations and borrowed developers, while the money flows to the shiny layers of the stack. Sovereignty Comes With Maintainers: Ten billion for chips and startups, a few hundred thousand for the code that keeps hospital websites safe. Links & Sources (all at sarahs-tech.eu): PHP security release and advisories, 21 October 2026 · The PHP Foundation on today's security release and its timeline · Wiz technical analysis of PHP2Shell · BSI, CISA, NCSC and CERT-EU warnings · Bitpage.de situation report on outages and hosters · BornCity on the 2024 audit, attack numbers and the Shodan count · AWS Security Blog on WAF mitigations · Cloudflare on its php2shell protections · heise, Help Net Security, SecurityWeek and BleepingComputer · Sovereign Tech Agency on its PHP investments · PHP Foundation on Open Collective · finews.ch and the Swiss Deep Tech Report 2026 · AP, Reuters and Xinhua on the protests in France; CyberPeace fact check · Bloomberg, Quartz, CNBC and the NVIDIA blog on Jensen Huang's tour and GTC Berlin · Trending Topics on Nvidia's share of European startup funding · TechCrunch and The Next Web on Pollen Robotics' Microduck · matrix.org and eGovernment on the Matrix Conference in Malmö · Cybernews and HR Dive on the University of Limerick study · Fortune and LinkedIn on women in AI hiring · previous episodes: Ep. 16 "The Kill Switch Is Not Where You Think", Ep. 17 "This Is European Tech", Ep. 20 "The Body of the Machine". Disclosure: Sarah Vailby is a synthetic host, AI-generated and disclosed in every episode under the AI Act's transparency rules. Her voice is synthetic. The Rasmus Lerdorf clips are original audio from Markus's 2017 interview for his former podcast "Menschen/Medien/Technologie"; background noise was removed with ElevenLabs, the words and voice are unchanged. Anthropic and OpenAI, whose models are used in producing this show, are credited among the finders of PHP2Shell. Markus works in web hosting; nothing here reflects an employer's position. Reports of Nvidia's agreement to buy Hugging Face are not confirmed as closed. Source state 24 October 2026. Feedback: Did your hoster switch your site off on Wednesday, or patch it quietly? Write to feedback@experten-system.de.
All sources — the FACIS survey, the Stack Overflow Developer Survey, the METR stopwatch study, the freelancer studies, the Article 50 guidelines and the Code of Practice with the icons — are linked in the show notes.
Are you the manager with the strategy, the developer with the trust problem, or the freelancer deciding whether to tell the client? Write to us — the best stories make it into a future episode, anonymously if you prefer.
Sarahs Tech — a show hosted by someone who doesn’t exist, with facts that very much do.
The sound that started Season 1, Episode 5 of Sarahs Tech was a heavy coffee mug slamming onto the table. It was the sound of my co-host, Sarah, running on three hours of sleep and absolute fury. Why?
Over the weekend, Washington drew a digital line in the sand. Anthropic pulled its top-tier Claude models offline globally. Why? Sudden US Department of Commerce export controls. Software treated like military hardware. The lockout was so strict it even affected Anthropic’s own European developers. Europeans are, once again, looking into an empty tube.
Sarah called it digital segregation. I call it architectural inevitable.
This episode was supposed to be a deep dive into the reports of Enrico Letta and Mario Draghi on European competitiveness. But the Anthropic shock proved the exact point I keep making: relying on centralized American monoliths is a high-risk strategy.
Digital Fiefdoms and Renters
We had an intense debate about why Europe regulators build beautifully formatted, GDPR-compliant cookie banners while Seattle-based hyperscalers manage 90% of all European corporate data. Sarah argues we are just a „digital colony“—renters in a house owned by Seattle.
We analyzed the regional contradictions:
The Nordic Mirage: Scandinavia is a tech paradise for user adoption (BankID, MitID), but architecturally, they national national islands that have handed the keys of the kingdom to AWS and Azure.
The French Compromise: Mistral AI preaches European independence, then immediately signs a partnership with Microsoft.
The Italian Guillotine: The data protection authority blocks everything first, prioritizing dignity over Roman jobs.
The Spanish Socket: Spain builds the physical data centers, Strain Strain its regional grid and water supplies, while profits and algorithmic intelligence fly back to California.
The Fragmentation of the US Monolith
While I understand Sarah’s frustration with European hesitation, she often praises the US as this perfect, frictionless monolith where scaling is easy.
That is a myth. In mid-2026, the US market is fracturing at a terrifying pace.
Culturally, localization is now essential (the massive economic superpower of the Hispanic population means you need Spanish-First deep local marketing). But more importantly, it is fracturing legally. Washington has completely failed to pass a federal privacy law. US states have taken over.
For a modern tech startup in the US, compliance is now a legal minefield spanning Arkansas, California (with its new Delete Act), Indiana, Kentucky, and Rhode Island. They are experiencing exactly the kind of Zersplitterung Sarah blames Europe for.
The Blueprint for Sanity: Federated Hybrid Strategy
It was here, looking at the Netherlands-based powerhouse Nebius Group, that we found our middle ground.
Nebius is building the heavy AI factories Europe needs, but they are architecturally locked into NVIDIA’s proprietary software trap. They are becoming high-end data foundries and power-grid providers for American models. As I told Sarah, they supply the electricity; California harvests the intelligence.
The corporate cloud silo is breaking down under its own legal and physical weight.
We cannot wait for permission. We must utilize global efficiency without surrendering local sovereignty. The future is not monolithic.
Our compromise is the Federated Hybrid Strategy. We use the global hardware networks—for compute power and raw engineering speed (shout-out to site.pro in Lithuania for pragmatic, Baltic code). But we keep our data governance and our execution layers completely local. We run local stacks (Ollama, Jan.ai) right on our desks. We build a network of sovereign, highly automated nodes that talk across borders without ever surrendering their core data.
We out-engineer the monopolies at a human scale.
Listen to the full debate and find the economic reports (Letta, Draghi) in our show notes on Substack. If you are a Baltic dev or part of the „clean code“ movement in Eastern Europe, I’d love to hear your take on the Federated architecture in the comments.
The Monolithic Myth & The Federated Compromise –
Sarah's Tech
Episode 5: The Monolithic Myth & The Federated Compromise
Can Europe survive as an independent tech ecosystem, or are we permanently trapped as digital tenants of foreign empires? In this high-stakes episode, Sarah and Markus strip away the polished corporate marketing of modern cloud tech. They analyze the immediate fallout of the sudden US tech embargo on advanced models, expose why the European single market remains a regulatory illusion, and establish a real-world architectural blueprint for digital sovereignty without losing commercial scale.
In this episode:
00:00–02:30: Cold Open: The Anthropic Embargo. Reacting to the breaking news of US export controls abruptly pulling Claude Fable 5 and Mythos 5 offline for all foreign nationals globally.
02:30–06:45: Act 1: The Single Market Fairytale. Dissecting the brutal realities of the Letta and Draghi reports, the 40% compliance tax on local startups, and telecom fragmentation.
06:45–12:30: Act 2: The Regional Tour. Deconstructing the Nordic digital mirage (MitID running on AWS), France's Mistral AI corporate compromises, Italy's data protection guillotine, and Spain's power-grid colonialism.
12:30–14:00: Sponsor Spotlight (site.pro): Stable, visually modifiable web architecture built to survive the tech debt of fragile AI prompt-to-code platforms.
14:00–18:15: Act 4: The Geopolitical Thriller. Analyzing the massive expansion of Amsterdam's Nebius Group and shattering the myth of a frictionless US market via state-level privacy fragmentation and the California Delete Act.
18:15–20:30: Act 5: The Federated Hybrid Strategy. Reaching a technical compromise: Out-engineering the monopolies by utilizing global hardware speed while maintaining local data governance via open weights.
20:30–22:00: Featured Outro Song: "Sarah's Tech Show" (The official pop-rock theme).
Key Takeaways:
The Deemed Export trap: Why US security panic can instantly paralyze international developers and European tech platforms overnight.
The electric socket dilemma: How hosting foreign server farms strains local utility grids while exporting the core algorithmic value back to California.
Why the monolithic market model is structurally dead on both sides of the Atlantic due to regulatory balkanization.
How to configure a zero-trust, automated corporate edge network using desktop open-weight architectures.
Links & Resources:
Ad Affiliate URL Sponsor): site.pro AI Website Builder (Pragmatic, stable, and client-proof)
Geopolitical Context: The US Export Control Directive on Anthropic Claude Fable 5 / Mythos 5 covered by Telepolis.
Official Reports: Enrico Letta’s "Much More Than a Market" and Mario Draghi’s EU Competitiveness Report (Available via the European Commission archive).
Sovereign Infrastructure: Nebius Group Amsterdam, plus local deployment engines Ollama and Jan.ai.
Newsletter & Analysis Archive: Sarah's Tech on Substack
Feedback: Are you ready to deploy a Federated Hybrid Strategy or are you staying locked in the corporate cloud cage? Share your network architecture or voice your thoughts via feedback@experten-system.de.
Neben meinem deutschen Podcast ‚Menschen Medientechnologie‘ hoste ich ab sofort einen neuen, englischsprachigen Feed auf dieser Domain. Zusammen mit Sarah Vejlby streite ich mich in ‚Sarahs Tech‘ über die Zukunft der europäischen Infrastruktur. Hier ist, worum es geht…“
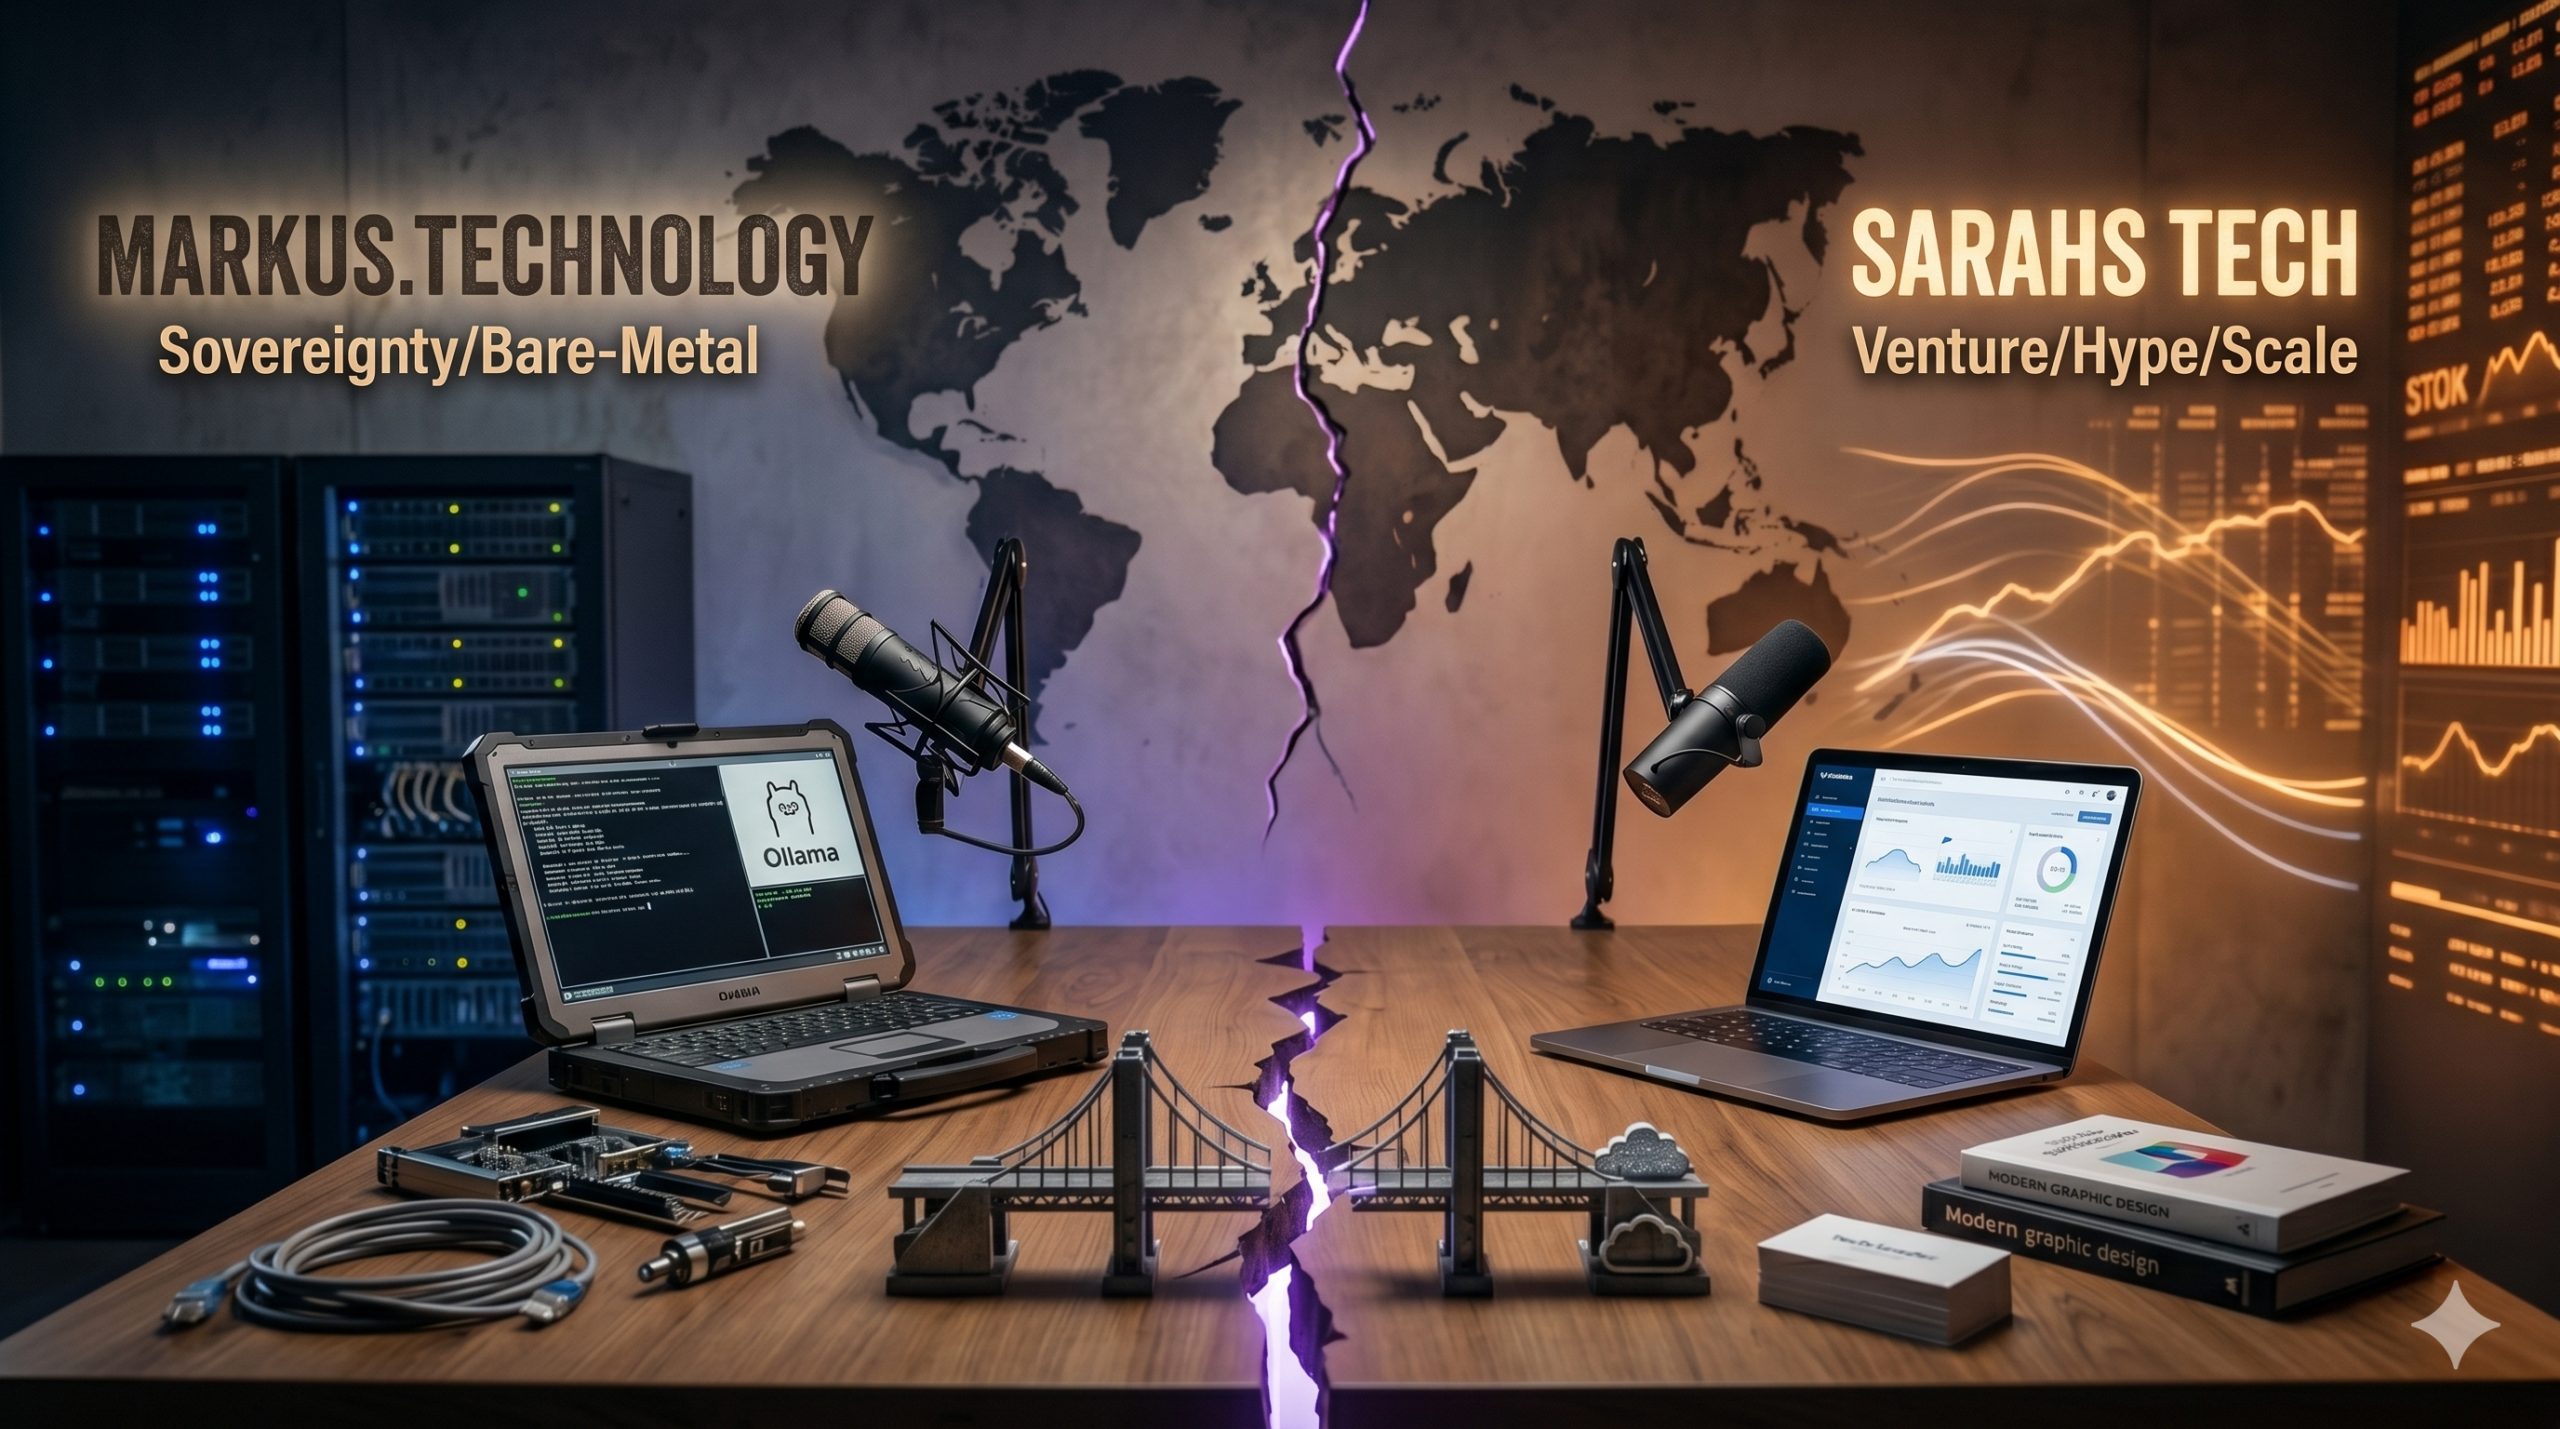
The digital landscape is fracturing, and sterile corporate tech podcasts simply don’t cut it anymore. That is why I am expanding the architecture of markus.technology to host a brand-new format: Sarahs Tech. This is not an echo chamber where two hosts politely nod at every new Silicon Valley marketing brochure.
Instead, it is an unpolished, high-stakes verbal sparring match between aggressive market ambition and bare-metal infrastructure reality. Sarah brings the high-energy drive for venture-backed speed and modern platform scaling. I anchor the debate in server-room facts, data privacy, and the critical necessity of European digital sovereignty. We don’t filter our thoughts, and we don’t fix the friction.
Our latest episodes tear down the glossy facades of the industry to look at the gritty geopolitical realities of 2026. We dissect the myth of the „European Digital Single Market“ using raw economic indicators from the Letta and Draghi reports. Coming up: We trace the economic thriller of Amsterdam’s Nebius Group scaling massive GPU clusters for US monopolies, and we dismantle the illusion of a homogeneous American market.
But we do not just complain about the „gilded cages“ of Big Tech. We actively build blueprints for operational survival—from running local, open-weight AI stacks via Ollama and Jan.ai right on your own desk, to engineering a resilient, Federated Hybrid Strategy for modern web agencies.
Sarahs Tech is fast-paced, sharp-tongued, and intentionally „unglätt“—designed for webmasters, developers, and tech leaders who want to hear what happens when macro-economic ambition clashes with sovereign engineering. The official podcast feed is hosted directly on this domain. If you are tired of sterile tech marketing and ready for real, structural trade-offs, add our XML feed to your independent podcast player, plug in your headphones, and join the architectural rebellion.
Find all episode from Sarah’s tech at Apple and Spotifiy. Listen for free.
Zustimmung
Diese Website verwendet Cookies verschiedener Art. Du kannst Cookies alle akzeptieren, alle ablehnen oder eine Auswahl treffen.
This website uses cookies to improve your experience while you navigate through the website. Out of these, the cookies that are categorized as necessary are stored on your browser as they are essential for the working of basic functionalities of the website. We also use third-party cookies that help us analyze and understand how you use this website. These cookies will be stored in your browser only with your consent. You also have the option to opt-out of these cookies. But opting out of some of these cookies may affect your browsing experience.
Necessary cookies are absolutely essential for the website to function properly. These cookies ensure basic functionalities and security features of the website, anonymously.
Cookie
Dauer
Beschreibung
cookielawinfo-checkbox-advertisement
1 year
Set by the GDPR Cookie Consent plugin, this cookie is used to record the user consent for the cookies in the "Advertisement" category .
cookielawinfo-checkbox-analytics
11 months
This cookie is set by GDPR Cookie Consent plugin. The cookie is used to store the user consent for the cookies in the category "Analytics".
cookielawinfo-checkbox-functional
11 months
The cookie is set by GDPR cookie consent to record the user consent for the cookies in the category "Functional".
cookielawinfo-checkbox-necessary
11 months
This cookie is set by GDPR Cookie Consent plugin. The cookies is used to store the user consent for the cookies in the category "Necessary".
cookielawinfo-checkbox-others
11 months
This cookie is set by GDPR Cookie Consent plugin. The cookie is used to store the user consent for the cookies in the category "Other.
cookielawinfo-checkbox-performance
11 months
This cookie is set by GDPR Cookie Consent plugin. The cookie is used to store the user consent for the cookies in the category "Performance".
CookieLawInfoConsent
1 year
Records the default button state of the corresponding category & the status of CCPA. It works only in coordination with the primary cookie.
JSESSIONID
session
The JSESSIONID cookie is used by New Relic to store a session identifier so that New Relic can monitor session counts for an application.
viewed_cookie_policy
11 months
The cookie is set by the GDPR Cookie Consent plugin and is used to store whether or not user has consented to the use of cookies. It does not store any personal data.
Functional cookies help to perform certain functionalities like sharing the content of the website on social media platforms, collect feedbacks, and other third-party features.
Performance cookies are used to understand and analyze the key performance indexes of the website which helps in delivering a better user experience for the visitors.
Analytical cookies are used to understand how visitors interact with the website. These cookies help provide information on metrics the number of visitors, bounce rate, traffic source, etc.
Cookie
Dauer
Beschreibung
__gads
1 year 24 days
The __gads cookie, set by Google, is stored under DoubleClick domain and tracks the number of times users see an advert, measures the success of the campaign and calculates its revenue. This cookie can only be read from the domain they are set on and will not track any data while browsing through other sites.
CONSENT
2 years
YouTube sets this cookie via embedded youtube-videos and registers anonymous statistical data.
Advertisement cookies are used to provide visitors with relevant ads and marketing campaigns. These cookies track visitors across websites and collect information to provide customized ads.
Cookie
Dauer
Beschreibung
IDE
1 year 24 days
Google DoubleClick IDE cookies are used to store information about how the user uses the website to present them with relevant ads and according to the user profile.
test_cookie
15 minutes
The test_cookie is set by doubleclick.net and is used to determine if the user's browser supports cookies.
VISITOR_INFO1_LIVE
5 months 27 days
A cookie set by YouTube to measure bandwidth that determines whether the user gets the new or old player interface.
YSC
session
YSC cookie is set by Youtube and is used to track the views of embedded videos on Youtube pages.
yt-remote-connected-devices
never
YouTube sets this cookie to store the video preferences of the user using embedded YouTube video.
yt-remote-device-id
never
YouTube sets this cookie to store the video preferences of the user using embedded YouTube video.